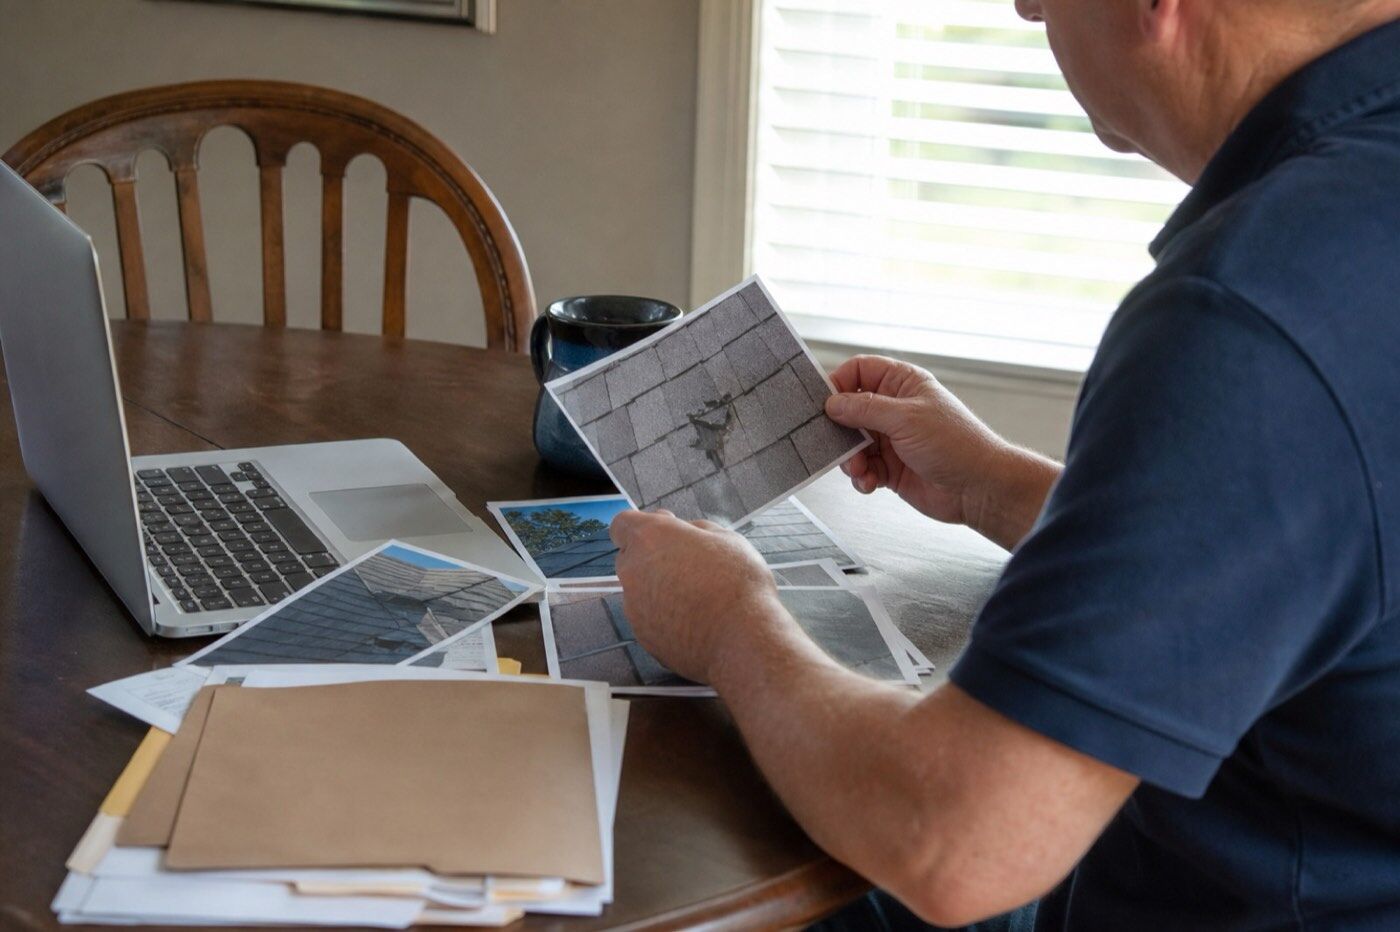
The short answer
After storm damage, the insurance process can feel confusing. A local partner roofer can inspect the roof, document damage with notes and photos and explain what repair or replacement would involve. Your insurance company decides whether the damage is covered, so start by calling them and asking what they need.
On this page
How does a roof insurance claim generally work?
- You document the damage and contact your insurance company.
- The insurer may send an adjuster to look at the roof.
- The insurer decides what is covered under your policy and tells you what it will pay.
- You choose a roofer and schedule the work.
Steps and terms differ by policy and insurer, so read through yours or ask your agent. This is general information, not legal or insurance advice.
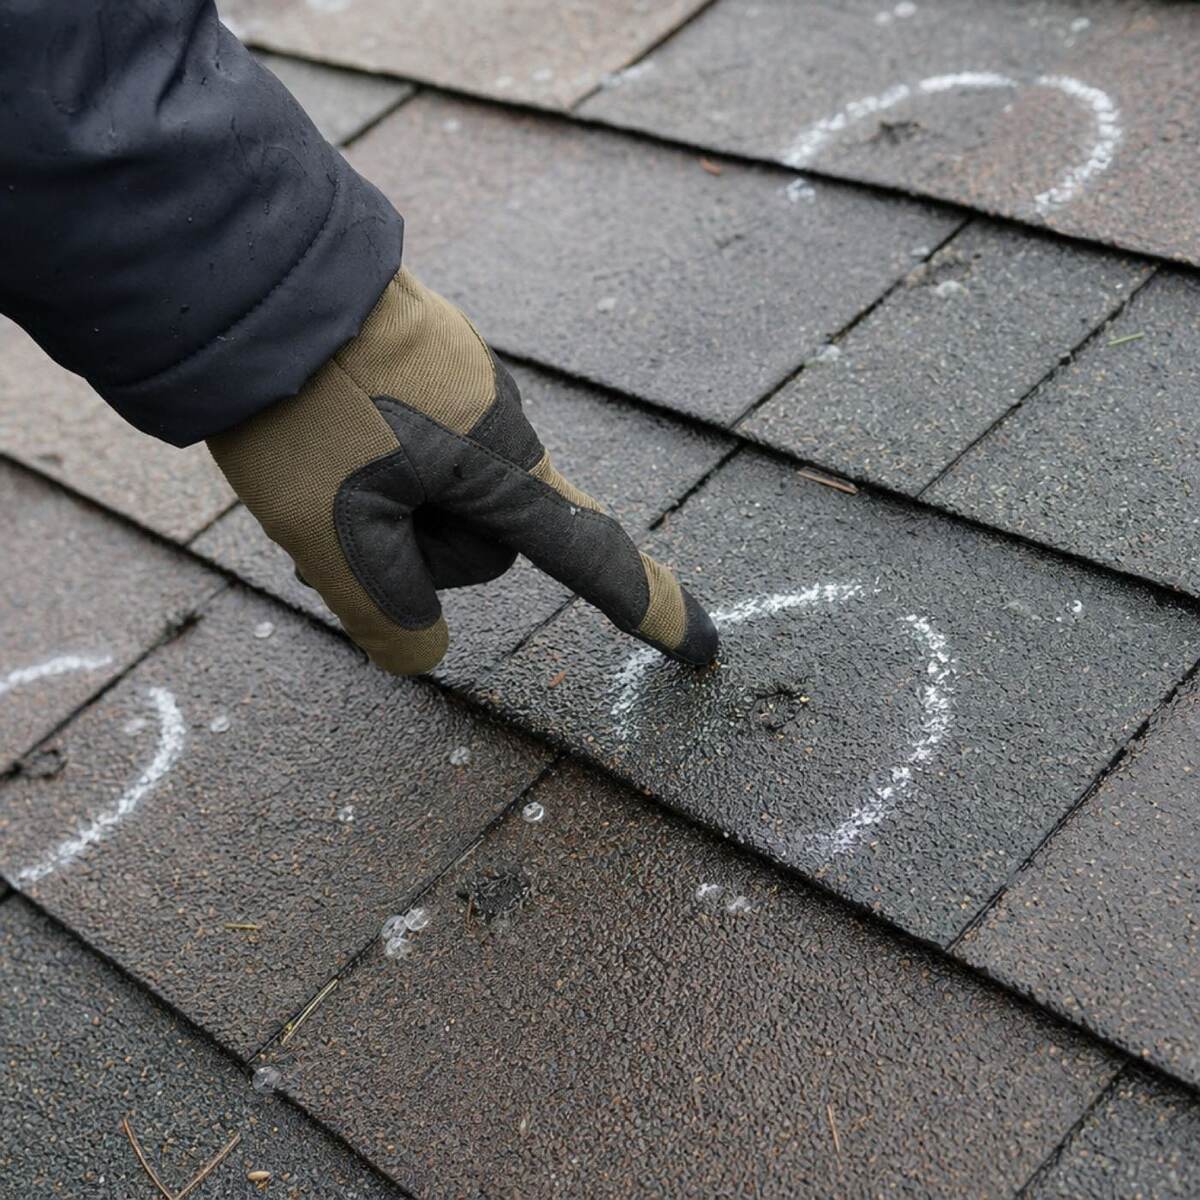
What should you document?
Dated photos of damage you can see from the ground, photos of the storm's effects on gutters, siding and vents, notes about when it happened, and any interior stains or drips. Keep receipts for temporary repairs such as a tarp.
What can a partner roofer do?
A partner roofer can inspect the roof, take photos and notes, and give you a written quote for the work. That documentation can help when you talk with your insurance company. The partner does not decide coverage and cannot promise what your insurer will pay.
What are the common stumbling blocks?
Policies often distinguish between sudden damage and wear from age, and they have deductibles. Waiting too long can make it harder to tie damage to a storm. Our guide on whether homeowners insurance covers roof replacement explains these terms in plain language.
Want a local pro to take a look? Request a quote and add a photo. Quotes provided by our network of licensed, insured local contractors to get you top quality at a fair price.
We serve Rochester · Byron · Kasson · Stewartville · Pine Island, and the surrounding Southeast Minnesota area.